F L A U N T


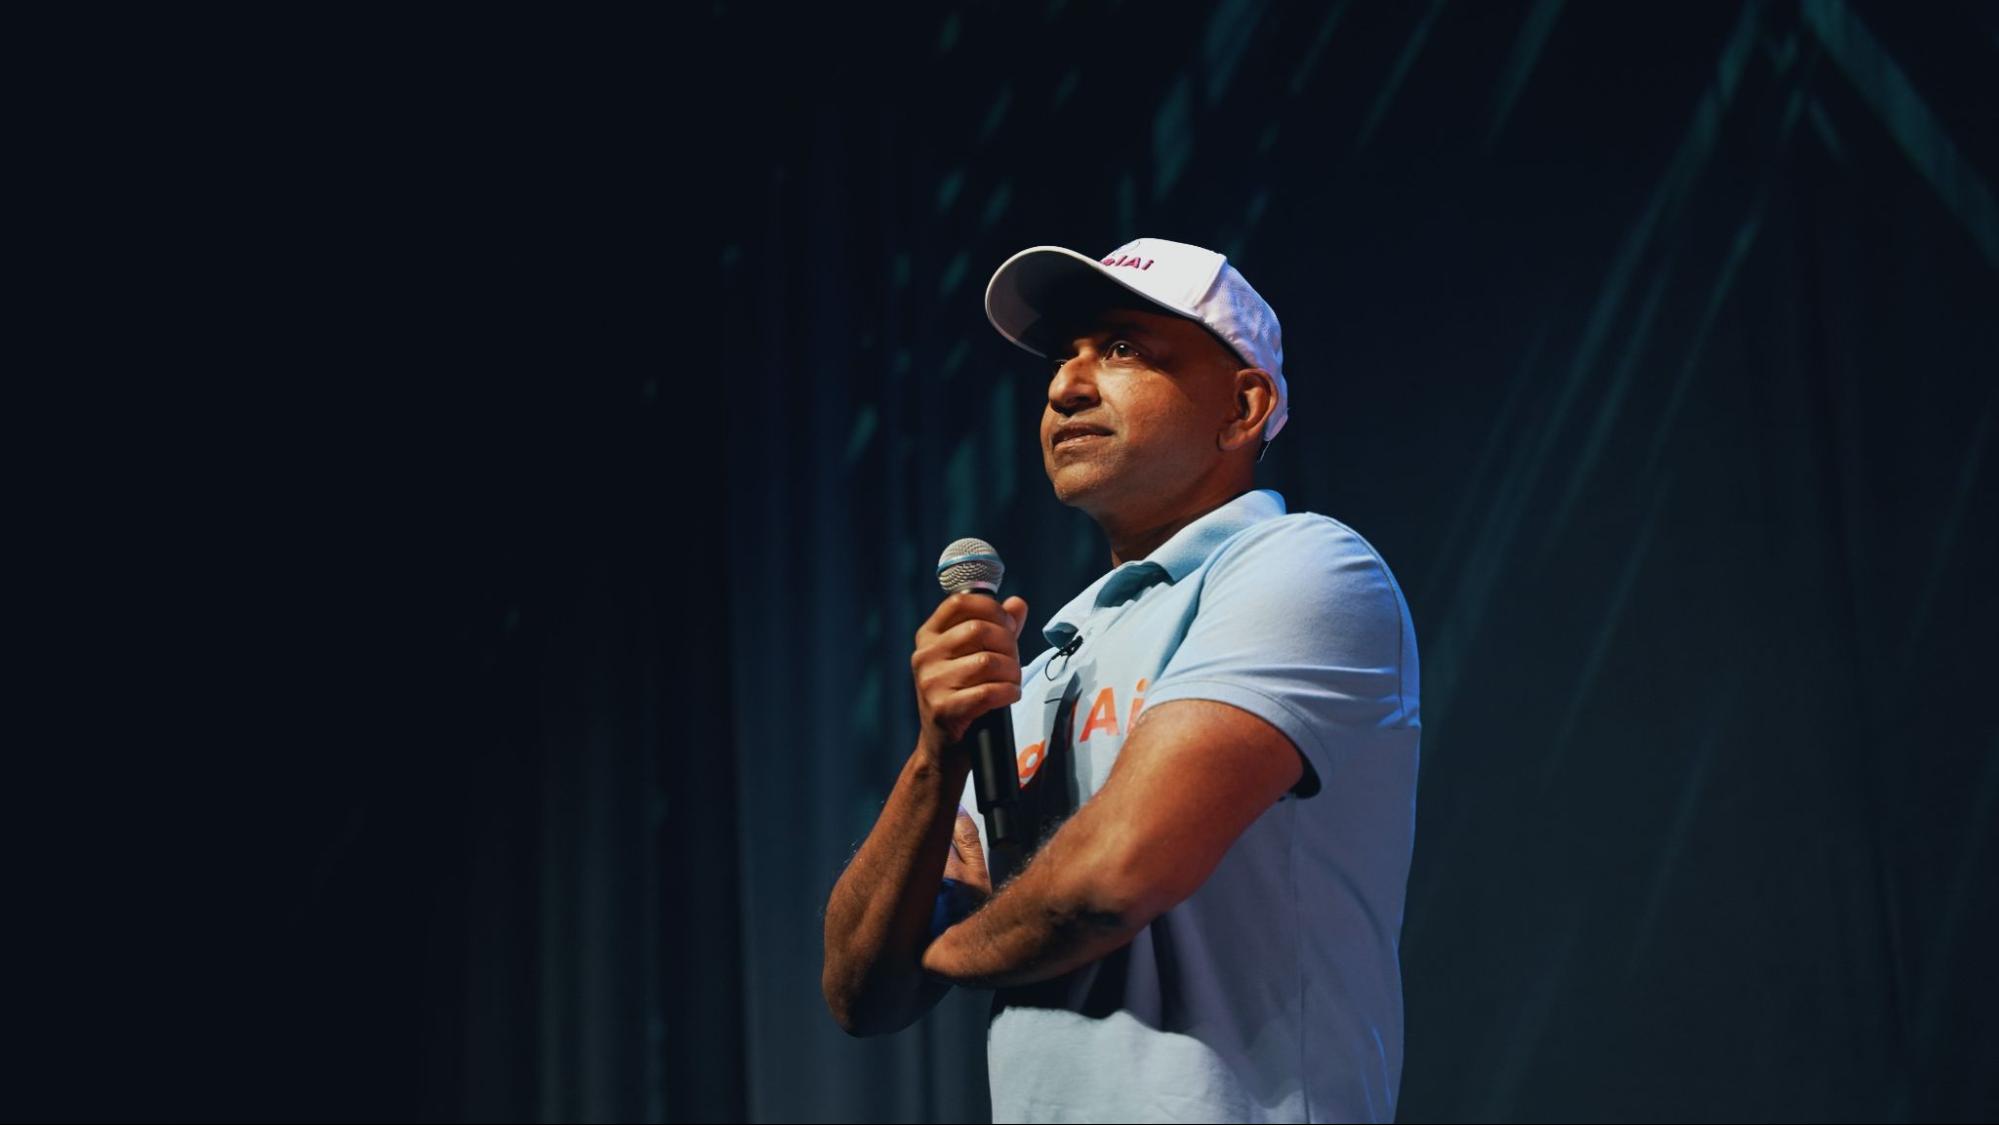
Pavan Agarwal works the floor at mortgage industry trade shows himself, in an AngelAi® shirt and jeans, talking to Realtors®, brokers, and loan officers one at a time. He answers his own messages. He hosts his own podcast on artificial intelligence and mortgages. None of that is a media strategy. It follows the same reasoning that governs how the software is built: the things a company depends on are the things its chief executive cannot hand to someone else.
"You cannot just slap AI onto an existing workflow," Agarwal said.
He runs Sun West Mortgage Company, Inc. (NMLS 3277), a national lender, and he created AngelAi, the conversational platform the company now runs on. He has been building toward both since 1983.
The Code Came First
Sun West was founded in 1980 by Hari Agarwal, a chemical engineer who approached lending the way an engineer approaches a reaction. He treated income, credit, assets, and collateral as the basic elements of a transaction, and he kept meticulous handwritten loan ledgers that recorded how each element behaved in each file. His son grew up inside that discipline.
Pavan wrote his first loan underwriting program in 1983. His first artificial intelligence program followed in 1985. Before he reached adulthood, he had already served nearly every role at Sun West, including wholesale representative, brand representative, and loan originator, and he had spent weekends mowing lawns, painting walls, cleaning bathrooms, and knocking on doors for the family business.
That order matters to how he talks about the technology. He did the manual version of nearly every task that AngelAi now performs, which is why he trusts the output.
"I know what the right answer is supposed to look like because I used to produce it by hand," he said.
It is an unusual route to the job. Agarwal came up through the code, inside the company he now runs.
What His Father Left Him
The operating standard is a question Hari repeated often enough that his son still applies it to files.
"Ask yourself if you would lend them the money and, if you would, how would you want to be treated as a customer?"
Hari was truthful with his clients to a fault, and he never held back knowledge from a family, even when candor cost him the sale. What he cared about was whether the family in front of him was making a good investment, not whether the deal closed. Pavan lost his father at the end of 2021, and carrying that philosophy forward became the work of the years that followed.
The Year the Company Changed Hands
In 2008, at the height of the financial crisis, Hari asked his son to take over. The timing was not chosen. Agarwal was in New York, working through a difficult collateral margin call, while Wall Street came apart around him. His father's message amounted to one sentence: get through this, and the company is yours to run.
He got through it, and he does not credit the trade.
"That trade only happened because my promise meant something to them," Agarwal said, referring to bankers he had known for years, several of whom would survive the crash. When those same people needed something later, he was there.
"My relationships saved me that day," he said.
It is the origin of a habit that now shows up everywhere in how the company operates. AngelAi's brand partnerships are with people whose own experience matches what the platform is meant to do, and Agarwal sought each of them out himself rather than through agencies. The arrangements are built to be substantive rather than transactional, which is part of why they have lasted.
The Work That Nobody Watched
The hands-on instinct is easier to admire than to sustain, and what it actually cost was decades of engineering with no audience.
Sun West was converting mortgage data into machine-readable, vectorized form throughout the 1990s. In 2006, the company launched an automated reverse-mortgage underwriting system it describes as the first of its kind. Then came a decision in 2012, more than a decade before the industry settled on the phrase "AI agents," to build the architecture out of self-generating units that replicate, evolve, and learn collectively rather than as one large monolithic system. The model came from biology. Stem cells replicate, evolve, and become the foundation of everything alive, and Agarwal saw no reason a lending intelligence could not be assembled the same way.
The years that followed were unglamorous and incremental. Cell architecture was developed quietly, with no product to show for a long stretch, which is precisely the point, because the head start was earned slowly rather than purchased. Only after all of it came a lending workflow that runs end-to-end, and the company reports seven years of that end-to-end operation inside Sun West. Some of the engineers who built it have been with the company for over twenty years.
"Real engineering is hard, specifically when you are trying to make something look simple," he said.
What that patience produced is a system the company calls a Transactional Language ModelTM (“TLM”), a deterministic engine in which the same inputs produce the same verifiable output every time, with every action logged and auditable. A general-purpose, probabilistic model can return two different answers to the same question. That variance is acceptable when the task is drafting text. It is not acceptable when the task is calculating a borrower's income and deciding whether that borrower will be able to realize the biggest financial decision of their life. AngelAi maps each piece of information to the lending concepts behind it. Take FHA, for example: a single reference to it connects to down payment requirements, the TOTAL scorecard, mortgage insurance premiums, and thousands of other related guidelines. The answer it produces is grounded in more than four decades of proprietary Sun West lending data rather than text scraped from the open internet.
Determinism is what makes the next part possible. Sun West stands behind AngelAi's answers with a conditional warranty, which the company describes as a first in the mortgage industry. Most artificial intelligence tools arrive with a disclaimer advising users not to rely on the output. This one arrives with a lender behind it.
The Part He Will Not Delegate
Agarwal's advice to other executives in regulated industries follows directly from how he spent those decades.
"Do not delegate your AI strategy to your IT department and hope for the best," he said.
A chief executive has to understand what the technology cannot do, not only what it can, because the limits are what tell you where not to spend. What he prescribes instead is slower, and he lays it out as three requirements: re-engineer the workflow, redefine what the jobs actually are, and treat compliance as an advantage rather than as red tape to route around.
That last requirement is the one most companies skip, and it is the one AngelAi was designed around. The platform is built to satisfy the overlapping framework of local, state, and federal lending rules. Traceability means every action carries a record of what was done, when, and why, so a decision on a borrower's income can be followed end-to-end. Auditability means a regulator, an external auditor, or a quality-control reviewer can independently verify that each step complied with the applicable rules. Explainability means the lender can always justify why a loan was approved, declined, or conditioned, with responsibility staying where it belongs. Those three principles are also what allow a lender to put a warranty behind an automated decision. The company reports more than 80 audits across HUD, Fannie Mae, Freddie Mac, and Ginnie Mae, with a clean record.
He describes his own role now as keeper of the vision for fair lending, meaning the person who understands the banking side and the technology side well enough to connect them.
What It Is All Aimed At
The problem Agarwal says he has been working on since childhood is narrower than the technology suggests. He watched families, disproportionately low-income and minority ones, never get onto the property ladder, and he never accepted financial literacy as the explanation.
"I saw it as a data problem," he said.
A loan file is data moving through a process, and an opaque, inconsistent, or biased process denies people who deserve credit. Applying the full library of federal, state, and county lending rules the same way on every file, in more than 100 languages, is his answer to that. Sun West carries the Home of Fair Lending® designation and serves borrowers with credit scores as low as 500, a range many large lenders exclude through overlays. The company reports higher FHA and VA approval rates than major lenders based on its comparison against FFIEC data.
The outcomes are where the argument stops being abstract. Lacy assumed homeownership was at least a year away, because her husband had been sick on and off for roughly fifteen years and the medical bills had damaged her credit. A free AngelAi credit-repair tool with no service fees* raised her score enough to qualify, and she moved through much of the process on her own. When she found a house, a new pre-approval letter reached her agent in ten minutes, and her offer was accepted within 24 hours. She said the platform changed her life and that she had not believed it was possible given her circumstances.
A veteran left significantly disabled after service, with credit damaged by the transition home, had been told no by lender after lender. AngelAi looked at the file individually rather than pushing it through a generic process. On signing day, a paperwork issue that would normally take days was resolved in about twenty minutes, and the family closed that same day.
Maria, a single mother, had been living with four family members in one room. It took about ten days from when she submitted her documents to when she received her keys. Her daughter's first reaction to her own bedroom was, "Mom, I finally have a room to myself."
Claire and Cole work with artificial intelligence systems professionally and went in expecting to find the seams. They closed in just over two weeks and described the process as really clean and really simple.
The company also built the system to keep those relationships rather than surrender them. In the conventional model, origination, underwriting, closing, and servicing sit on separate systems, and the moment a loan closes, the borrower is handed to a different servicer. AngelAi keeps the borrower inside a single closed loop through its Red Carpet Servicing System, so the data, the underwriting decisions, and the logic behind them all carry forward into servicing instead of disappearing in a handoff. The same system that originates a loan continues to service it for the life of that loan, whether that means a single thirty-year term or several refinances across a borrower's life.
The measure Agarwal says he actually applies has nothing to do with any of that.
"The technology only matters if a grandmother who has never turned on a PC can use it," he said.
It passed that test. A first-time user can complete a full home-financing process simply by talking to the platform, which is the standard Empathetic Technology™ was built to meet, and it is the quality Fast Company recognized with a 2025 Innovation by Design Award.
Still on the Floor
What connects the teenager writing underwriting code in 1983 to the chief executive in a t-shirt at a conference booth is that he has never handed off the part that decides the outcome. He produced the answers by hand, then built the system that produces them, and now spends much of his week explaining it to people in person. He reports having personally invested more than $150 million into AngelAi and its research arm, Celligence, and describes the company as debt-free and founder-funded rather than venture-backed.
The ambition now extends past mortgages toward a full-spectrum finance ecosystem, including credit boost, microfinance, financial planning, wealth management, retirement planning, healthcare financing, property management, tax filing, credit cards, and insurance. The logic is that a system that can solve the most complex and heavily regulated credit market in the world can solve credit almost anywhere. The promise underneath it all is printed on the banner behind him at every booth: Nothing Is Beyond Reach™.
"Everyone should have fair and unbiased access to financial security," he said.
He has been at that specific problem for more than forty years.
Disclaimers:
*Credit Boost through AngelAi is subject to restrictions and charges (see angelai.com/terms).
AngelAi and Transactional Language Model are the registered trademarks of Celligence LLC.
Visit angelai.com/warranty for terms and limitations of the AngelAi Warranty.
Realtors, Fannie Mae, Freddie Mac, and Ginnie Mae are registered trademarks of National Association of Realtors, Federal National Mortgage Association, Federal Home Loan Mortgage Corporation, and Government National Mortgage Association, respectively.
Sun West Mortgage Company, Inc. and Celligence LLC are not affiliated with any third parties. The names are owned by the respective third parties.
About AngelAi:
AngelAi has been developed by Celligence LLC, one of the fastest growing fin-tech and AI companies. Celligence has engineered a novel AI that is evolving and self-generating neural cells which come together to solve complex problems. The Celligence AI is deterministic, not merely generative, and it delivers 100% accurate and trustworthy responses, as is required for financial transactions.
At Celligence, a team of brilliant engineers is expanding the boundaries of the financial services industry through innovations in mobile applications, customer acquisition, retention algorithms, and AI-based process automation, continuously filing new patents supporting our technology.
AngelAi has a licensing agreement with Sun West Mortgage Company, Inc. NMLS 3277 to deliver superior quality financial services. Mortgage and other financial services are provided by Sun West Mortgage Company, Inc. NMLS 3277. Celligence LLC is an affiliate of Sun West Mortgage Company, Inc.
About Sun West Mortgage Company, Inc.
At Sun West we dedicate ourselves to offering an amazing experience to our customers. To accomplish this, we empower our loan officers so that they can find great rates and provide attractive and appropriate loan options for each customer – at amazing speed. Our focus on technology has given us an edge in the mortgage industry to offer exceptional turn times so the customers can get into the home of their dreams sooner!
We are committed to our core values of people, experience, technology, and product. Sun West was founded in 1980 with the perspective of “customers first” and the desire to make the mortgage process easy and stress-free for prospective and refinancing homeowners. Since then, Sun West has developed a multi-billion-dollar loan portfolio and is licensed in 50 states, the District of Columbia, Puerto Rico, and the US Virgin Islands. Our 45 years of experience have been passed down to everyone here at Sun West through excellent leadership and capabilities.
For licensing information, go to: www.nmlsconsumeraccess.org. Visit www.swmc.com/disclaimer for the full list of license information. Please refer to www.swmc.com/TXdis to view Texas Complaint Notice and Servicing Disclosure. In all jurisdictions, the principal (main) licensed location of Sun West Mortgage Company, Inc. is 18303 Gridley Rd, Cerritos, CA 90703, Phone: (800) 453-7884.
Stay up-to-date with exclusive events and content.


